 English

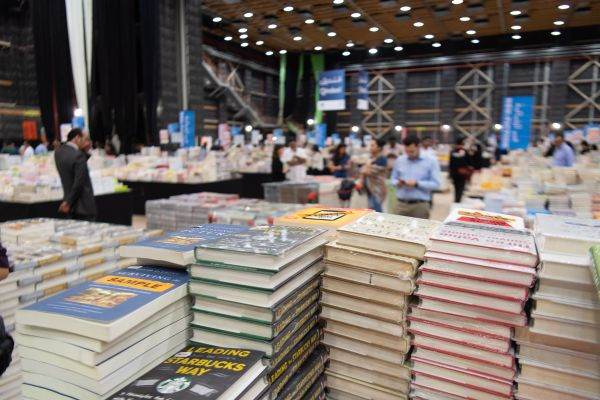
Europeans continue to read, yet publishers and writers are concerned for a variety of reasons. The European book market generated revenues of approximately euro24.9 billion in 2024 - a 2.2% increase over the previous year - though this rise in value does not reflect a corresponding increase in the number of volumes sold. Germany, the UK, France, Spain, and Italy rank among the continent's major markets. While printed books continue to dominate sales, audiobooks are gaining ground.
The European book industry is maintaining its economic scale, but revenue trends must be viewed in the context of inflation and production costs. According to the Federation of European Publishers (FEP) - in its "European Book Publishing Statistics 2024" report published in November 2025 - publishers' revenues from book sales reached approximately euro24.9 billion in 2024, up from euro24.4 billion in 2023 and euro23.9 billion in 2022. The 2026 report is expected to highlight further causes for concern. The total market value, calculated to include sales of books published by European houses as well as trade margins, is estimated at euro36.1 billion. Consumer spending on books ranges between euro37 billion and euro39 billion, according to the same organization. These figures rely on different indicators and should not be confused with publishers' net revenues.
However, rising revenues do not mean that Europeans are buying more books. The FEP projects sales of approximately 2.5 billion copies for 2026, and recent trends point to a decline in sales volumes. Furthermore, although publishers' nominal revenues have surpassed previous historical highs, their real economic power remains below past levels. According to data presented by the FEP at the Frankfurt Book Fair, inflation-adjusted revenues fell to approximately euro15.5 billion in 2024, down from euro22.2 billion in 2007. This gap indicates that the rise in receipts has not fully offset the general increase in prices, and publishers must manage their margins within a more challenging economic environment.
• Germany, the UK, and France lead the rankings
The European market is concentrated in a few large economies with strong publishing traditions and extensive distribution networks. Germany, the UK, France, Spain, and Italy rank among the leading markets in terms of publisher revenues, according to the FEP. Cross-country comparisons require caution, as national statistics may employ different methodologies, and publisher revenues are not equivalent to the total value of sales to consumers. France offers a pertinent example of the pressures facing the industry. According to the "Syndicat national de l'edition" (SNE)-the trade association for French publishers-the country's publishing turnover fell from euro2.945 billion in 2023 to euro2.902 billion in 2024, a decline of 1.5%. The number of copies sold dropped from 439.7 million to 426 million, a decrease of 3.1%. The comparison between value and volume is telling: revenues may remain relatively stable or even rise during certain periods, even as the number of books purchased falls. For publishers, such a trend can translate into higher costs per copy and an increased reliance on pricing strategies, the success of new titles, and inventory management.
• Print books dominate, yet digital formats are strengthening their position
Digital transformation is gradually altering consumption habits without displacing the supremacy of the printed book. According to FEP data presented in Frankfurt, print volumes accounted for 82.9% of European market revenue in 2024. E-books held a share of approximately 13%, while audiobooks reached 4.2%-making this one of the industry's most dynamic segments. Commercial distribution also remains a key factor. Physical bookstores generated 48.2% of market revenue, while online sales accounted for 23.5%, according to the FEP presentation from October 2025. These figures show that traditional bookstores continue to play a central role, even though online stores and digital platforms have changed the way readers discover and purchase titles. For publishers, diversifying formats means new distribution opportunities, but also the need for investment in production, copyright, and promotion.
Audiobooks can leverage previously published titles, while e-books facilitate cross-border access without the logistical costs associated with physical distribution.
• Approximately 580,000 new titles in a single year
The European publishing output remains highly diverse. In 2024, publishers publ at approximately 580,000 new titles, according to the FEP-slightly below the level of around 585,000 titles seen the previous year. The available book stock reached approximately 14.3 million distinct titles, 3.4 million of which were in digital format. The largest catalogs are reported in the UK, Germany, Italy, France, and Spain. The scale of this offering points to an active publishing sector but also raises an economic issue: in a market where hundreds of thousands of titles appear annually, visibility and distribution become essential for commercial success. A high number of new releases does not automatically guarantee high sales, and publishers must balance investments in new titles with the leveraging of their existing catalogs.
According to the FEP, the entire book value chain-from authors, publishers, and booksellers to printers and designers-supports over half a million jobs in Europe.
• Prices rising more slowly than the cost of living
One of the industry's main challenges is the gap between the trend in book prices and general inflation. The FEP has shown that book prices rose by 38.3% over the last 20 years, compared to a 64.1% increase in the general price level.
This disparity limits publishers' ability to pass rising costs on to buyers in full. At the same time, the rising cost of paper, printing expenses, transport, and promotion can impact profitability - particularly for small publishers, who have lower production volumes and less bargaining power. Demand is not without its risks, either. Eurostat data show that 47.2% of Europeans aged 16 and older do not read books. A lack of interest -rather than the price of books - is the primary reason cited. This indicator suggests that expanding the readership remains a structural challenge for the industry.
The European book market boasts a solid economic foundation, an extensive range of titles, and diverse distribution channels. However, the figures indicate that revenue growth in value terms is insufficient to demonstrate a genuine consolidation of the industry.
For the European publishing industry, the challenge lies not merely in selling higher-priced books, but in retaining the existing audience, attracting new readers, and translating market scale into sustainable growth.








 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur































Reader's Opinion