 English

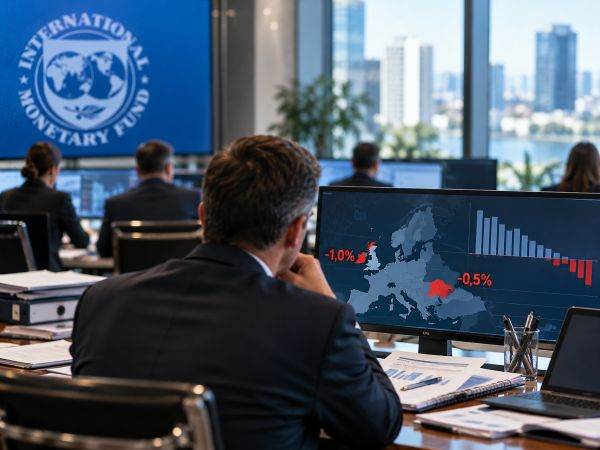
The International Monetary Fund (IMF) issued an urgent call yesterday for advanced economies and other nations to cut government spending, reduce deficits, and lower debt levels, warning that delaying these measures would only make their implementation more difficult in the years ahead, according to Reuters.
Rodrigo Valdes, Director of the IMF's Fiscal Affairs Department, stated that rising sovereign bond yields are intensifying fiscal pressures at a time when the average public debt is on track to reach 100% of Gross Domestic Product (GDP)-the highest level since World War II-leaving countries with little room to maneuver or delay action.
"It is an urgent matter, and action must be taken now because conditions have changed," Valdes said, highlighting risks stemming from inflationary pressures, high global debt levels, and rising sovereign bond yields. "So, if you want a simple message: we have emphasized the urgency of our call," Valdes noted.
Ahead of the IMF and World Bank annual meetings taking place this week in Bangkok, Valdes told Reuters that "fiscal outcomes this year are weaker than anticipated six months ago and weaker than those of a year ago." Most countries are currently considering increasing spending rather than adopting austerity measures, Valdes noted.
• Strengthening political support is essential
Rodrigo Valdes stated that the challenge for major advanced economies facing high debt levels lies in securing political support for concrete plans to contain medium-term financing costs and limit spillover effects to the rest of the world.
"The longer countries wait, the more painful the adjustment becomes," the IMF emphasized in an article published yesterday on the institution's blog. Delaying adjustments would increase the interest burden and fiscal vulnerabilities, further narrowing economic policy options.
Financing conditions for many emerging and developing economies have remained favorable, but this situation could change, the IMF noted, urging these countries to reduce fiscal vulnerabilities and strengthen debt management.
Low-income countries, where access to external financing was already difficult, need to strengthen their fiscal systems and improve spending efficiency, the IMF added.
According to the institution, high oil prices, persistent inflation, increased demand for investment, and the faster-than-expected expansion of artificial intelligence have led to sharp increases in long-term government bond yields in recent months. The average yield on 10-year government bonds in G7 nations rose by more than 110 basis points between February and September, reaching its highest level in nearly two decades, the IMF stated.
According to the international financial institution, the average effective cost of government financing is projected to rise to 3.7% by 2031, up from 2.3% in 2021. In the US, interest payments were forecast to reach 5.3% of GDP, an increase from the 2.8% of GDP recorded prior to the Covid pandemic. This figure is even higher in low-income countries, where interest payments currently consume over 15% of tax revenues, compared to an average cost of approximately 9% during the 2011-2019 period.
An additional source of strain was the fact that governments in advanced economies refinanced a larger share of their debt over shorter maturities, leading to a faster pass-through of higher interest rates to government borrowing costs, the IMF noted. For G7 countries and Spain, the share of debt maturing within one year is currently approaching 30%, the institution added.
Inflation rates exceeding targets and higher energy prices suggest that central bank policymakers may need to keep interest rates elevated for a longer period; This, in turn, would limit governments' ability to respond to a recession, precisely at a time when demands for increased spending on defense, energy security, and the needs of aging populations are intensifying.
The IMF noted that, currently, interest rates on public debt in several countries exceed projected nominal growth rates, which will make stabilizing their debt even more difficult.
Valdes noted that an increasing number of countries are allowing the costs resulting from high energy prices to be passed on to consumers, yet many continue to rely on costly, broad-based measures to protect their populations.
"We estimate that, overall, the fiscal cost of all these measures amounts to approximately half a percent of global GDP," the IMF official stated, emphasizing that maintaining such measures would drive up global prices.
• IMF: 0.5% decline for Romania's economy this year
The International Monetary Fund (IMF) has lowered its forecast for Romania's economic performance this year, projecting a 0.5% contraction-down from the 0.7% growth forecast in April and the 1.4% growth projected in October of last year-according to the latest "World Economic Outlook" report published by the international financial institution on Tuesday, Agerpres reports.
The IMF also slightly reduced its forecast for Romania's GDP growth in 2027 to 2.2%, down from the 2.5% projected in the spring.
According to the international financial institution, the only countries in Europe-across both advanced and emerging economies-expected to record a contraction in Gross Domestic Product this year are Romania (-0.5%) and Ireland (-1%). Overall, Europe is set to record economic growth of 1.4% this year and an expansion of 1.7% in 2027.
The IMF is also more pessimistic regarding Romania's progress in narrowing its current account deficit; according to the latest estimates, the deficit will drop to only 7% of GDP this year, compared to the 6.8% of GDP forecast in the spring. A similar trend is expected next year, with Romania's current account deficit projected to fall to 6.7% of GDP-a more modest outcome than the 6.2% of GDP forecast in April. The IMF has also significantly revised its forecasts for consumer price trends in Romania, projecting an annual average of 8.2% in 2026 and 4.1% in 2027. By comparison, in April, the Fund had projected an average annual price increase of 7.8% for Romania in 2026 and 3.9% in 2027.
Regarding Romania's unemployment rate, the IMF indicates it will rise to 6.5% in 2026-up from 6.1% in 2025-before easing slightly to 5.9% in 2027. In contrast, the April forecast anticipated a slight drop in the unemployment rate to 6% in 2026, followed by a decline to 5.9% in 2027.
Globally, the International Monetary Fund has slightly upgraded its growth estimates for 2026, describing a world economy caught between rising energy prices and the AI investment boom. According to the latest forecasts presented in Bangkok, the IMF expects the global economy to grow by 3.1% this year (0.1 percentage points above the July forecast) and 3.5% in 2025, before accelerating to 3.4% in 2027 (unchanged). The revision stems from the strong performance of advanced economies-particularly in Asia-fueled by the artificial intelligence investment boom: the US (expected growth of 2.3%, unchanged despite the energy shock), Taiwan (10.7%), South Korea (3.3%), and others.
In contrast, emerging economies are suffering from rising hydrocarbon prices triggered by the conflict in the Middle East; they are attempting to mitigate this impact through subsidies that further deplete their already limited budgetary resources.
At the same time, energy-importing countries not exposed to the AI boom remain the most vulnerable-a "two-speed" trajectory, the Fund notes.
"The global economy has demonstrated resilience, but that resilience is being tested, with downside risks," warns Silvana Tenreyro, Chief Economist at the IMF.
Last week, the World Bank released its own forecasts, projecting that Romania's economy would contract by 0.5% this year due to fiscal consolidation and higher energy costs. A recovery in real incomes and slowing inflation should help growth rebound to approximately 1.9% in 2027-2028, following the decline in 2026.








 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur































Reader's Opinion