 English

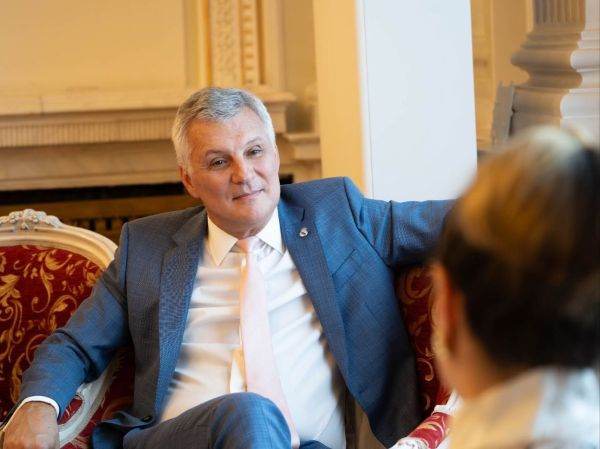
The pledge to refund excess payments made on ROBOR-linked loans cleared Senate committees yesterday, yet the path to compensation promises to be contentious. Legislative bill L447/2026, initiated by PSD Senator Daniel Zamfir, received a favorable report from the joint committees-specifically, the Committee on Budget, Finance, Banking, and Capital Markets, and the Committee on Economics, Industries, Services, Tourism, and Entrepreneurship. While the initiator hails this as a victory under the slogan "Give the money back!", Maria-Gabriela Horga, Chair of the Budget Committee, warns that the initiative raises false hopes and could harm the banking system. According to political sources, the bill could face a new hurdle right at the start of Wednesday's plenary session: a request to remove it from the agenda and send it back to committee.
The bill provides for the recovery of additional amounts paid by consumers whose borrowing costs were affected by anti-competitive practices or interest calculation errors. While the favorable joint report brings the initiative closer to a Senate plenary vote, it does not amount to the law's adoption or the immediate triggering of payments to bank customers. Daniel Zamfir immediately announced the outcome on his Facebook page in a post combining the promise of compensation with a political attack: "Give the money back! Today, in the Budget Committee as well, I secured a favorable report for the bill requiring banks to compensate consumers affected by "inflated' ROBOR rates. The vote in the Senate plenary session is scheduled for Wednesday. Who do you think opposed it? You get just one guess..." The post is accompanied by the hashtags "#NoAbuses" and "#NoUSR."
The favorable outcome concerns the joint report of the two committees. According to information provided to the newsroom, votes from the Economic Committee tipped the scales in favor of approval when results were aggregated, given the numerous abstentions in the Budget Committee-where there were only 7 votes in favor and 10 abstentions. This voting pattern indicates that the bill is heading to the plenary session amidst disagreements that could cause issues during the final vote. Political sources suggest that some of the senators who abstained intend to request-at the start of Wednesday's plenary session-that the bill be removed from the agenda and sent back to committee. If such a request is made and approved, the vote announced by Social Democratic Senator Daniel Zamfir could be postponed. Maria-Gabriela Horga, Chairwoman of the Committee on Budget, Finance, Banking, and Capital Markets, stated: "The bill initiated by the PSD is yet another example of cynical populism that will not yield the results promised by its sponsors. Those who currently hold or have held a bank loan stand to gain nothing. In fact, those seeking a loan might actually lose out! However, the bill could have systemic repercussions for commercial banks and, above all, for confidence in Romania's banking sector. Trust is a bank's most valuable asset, and a free economy cannot function without a healthy banking system. I suspect that, despite all the political noise made in the Senate today, it will ultimately be the PSD itself that blocks the bill in the Chamber of Deputies. This has been the PSD's modus operandi for several election cycles: they raise people's hopes, only to dash them later."
Beyond the political wrangling, bill L447/2026 proposes a mechanism with direct implications for loan agreements. Whenever an investigation by the National Authority for Consumer Protection or the Competition Council establishes that borrowers have suffered harm due to anti-competitive practices or proven errors, the responsible credit institutions would be required to rectify the errors, recalculate the obligations associated with all affected contracts, and provide full restitution for the proven damages. Affected consumers could request a contract review within 45 days of the harm being formally established via an administrative document. The bill provides for the suspension of the effects of the variable interest rate clause from the time the request is submitted until it is resolved, whether amicably or through court proceedings. This suspension would remain in effect for the duration of the lawsuit should the borrower choose to seek redress in court. The bank would be required to submit a written proposal for contract revision, including a detailed breakdown of the recalculation and the total amount of loss incurred. Reimbursement would be contingent upon the consumer's written agreement to the bank's proposal. Once accepted, the credit institution would have 15 days to make the payment. The borrower could choose between having the funds transferred to a separate account or having the principal balance reduced, provided the loan is still active. Non-compliance with the law would be punishable by a fine ranging from 0.5% to 1% of the credit institution's turnover for the pr The ROBOR scandal erupted in early June when the Competition Council, following an extensive investigation, stated that ten banks participating in the fixing process had coordinated their behavior over recent years when setting the index used to calculate variable interest rates. As a result of the investigation, the Competition Council imposed fines totaling 3.73 billion lei-equivalent to approximately 710 million euros-for violations of competition rules. All fines have been challenged in court.









 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur































Reader's Opinion