 English

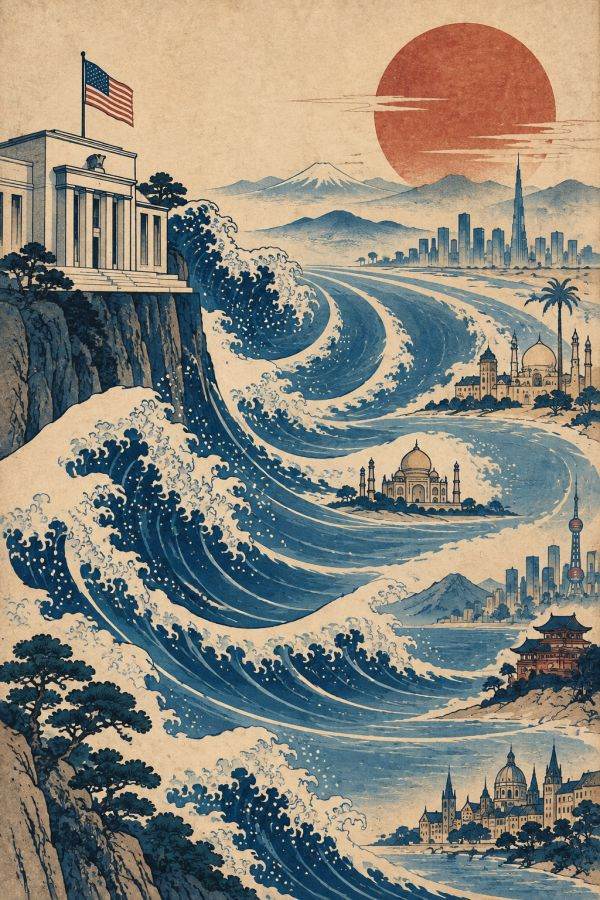

Central banks in five Gulf states raised interest rates on the same day as the US Federal Reserve (Fed), the Indian rupee crossed the 96-per-dollar threshold, while China maintains its own monetary policy. This same Fed decision illustrates the extent to which individual nations can determine their own interest rates, exchange rates, and capital flows, and where US interest rates cease to dictate capital allocation.
• The Fed's Decision
The Federal Open Market Committee (FOMC)-the Fed body responsible for setting interest rates-voted 12-0 on Wednesday, September 16, to raise the target range for the benchmark interest rate by 25 basis points to 3.75%-4%, according to a statement issued by the US institution. This marks the first Fed rate hike since July 2023, according to Yahoo Finance. In his press conference statement, Fed Chair Kevin Warsh noted that inflation has remained above target for over five years and that price stability is, therefore, the priority for the institution he leads. Inflation has risen since the beginning of the year against the backdrop of the war with Iran, according to CNN.
Details of the decision, political reactions in Washington, and consequences for the US economy are covered in the • BURSA• article accompanying this analysis. This analysis examines how the Fed's rate hike impacts regions outside the United States. The facts are drawn from external sources, cited at each point. The explanation of the mechanism comes from two works published by BURSA: • Interest Rate Theory• (Florian Goldstein, BURSA Publishing House, 2026) and the "Analysis of Economic Blocs" dossier. Wherever the analysis adds its own interpretation, the text explicitly states so.
• What was conveyed in the first two days
The hike was largely anticipated: in the hours leading up to the announcement, the market assigned it a probability of around 90%, according to Yahoo Finance. Consequently, some of the market movements described below reflect the anticipation of the decision, not just the decision itself.
The Fed's Board of Governors raised the interest rate paid to banks on reserves held at the Fed to 3.90%, effective September 17, according to the implementation note published by the Fed. On the same day, the Central Bank of the United Arab Emirates raised its benchmark rate to 3.90%, the Central Bank of Saudi Arabia raised its repo rate to 4.50%, and the central banks of Oman, Qatar, and Bahrain each implemented 25-basis-point hikes, according to Arab News. Kuwait kept its discount rate at 3.5%, as the Kuwaiti dinar is pegged to a basket of currencies rather than solely to the dollar.
The dollar index rose 0.7% on Wednesday and stood at 100.33 points on Thursday-its highest level against major currencies, including the yen and the euro, in seven weeks-according to Reuters. On Thursday, the Indian rupee crossed the 96-per-dollar threshold for the first time since July, following the Fed's rate hike and amidst high oil prices, according to the Free Press Journal. On Thursday in Asia, the MSCI index of Asia-Pacific shares excluding Japan rose by 0.4% and the Nikkei climbed 0.5%, while major Chinese stocks fell 0.4% and the Hang Seng dropped 0.9%, according to Reuters.
Other major central banks are moving in the same direction. On Thursday morning, Reuters reported that the Bank of England was expected to hold interest rates steady, while the Bank of Japan was expected to raise them on Friday to their highest level in 31 years, according to Reuters (as cited by Yahoo Finance). Joe Brusuelas, chief economist at RSM, wrote in a note cited by Yahoo Finance that major central banks are reaching a consensus: after a period of treating price shocks as temporary, they now aim to halt inflation before it spreads. In a statement from the press conference published by the Fed, Warsh noted that most advanced economies are facing price pressures and that each central bank makes decisions based on its own specific mandate.
• How a Fed interest rate hike is transmitted
Interest rate theory begins with a simple observation. A firm or a bank borrows money to buy low in one market and sell high in another, or to invest where the return is higher. The transaction is undertaken only if the resulting profit margin covers the interest paid and other associated costs. Interest rate theory refers to this as the "hurdle rate" function of interest: the interest rate determines which credit-financed operations remain profitable and, consequently, where capital is allocated. Interest rate theory does not separately address the interest rate set by a central bank. The present analysis supplements the theory in this regard with a specific interpretation: the Fed's interest rate serves as the baseline cost for any dollar-denominated loan, with the risk premium and the cost of barriers between economies added on top. When the Fed raises the interest rate by 25 basis points, any dollar-financed operation must generate higher returns to remain profitable. Operations where the earnings only slightly exceeded the previous cost credit become unprofitable and cease. Consider an illustrative example: a company borrows in dollars at an annual interest rate of 6% to purchase goods, which it then resells at a 6.2% annual return. The company retains a margin of 0.2 percentage points. If the interest rate on the company's loan rises to 6.25%, the operation results in a loss, and the company abandons it.
The rate hike does not remain confined to the United States. Interest rate theory indicates that a tightening of financial conditions in a major monetary hub propagates to the rest of the world through risk channels, financing mechanisms, and arbitrage-affecting even economies that do not use that hub's currency.
Interest rate theory also describes the influence of the dominant monetary hub: it drives up expected inflation and risk premiums in other economies. In practice, investors shift capital toward higher-yielding US securities; consequently, other countries' currencies depreciate, and dollar-denominated imports become more expensive.
Investors do not always wait for the official decision before acting. In India, for instance, foreign portfolio investors sold Indian equities worth approximately 13,138 crore rupees during the first half of September-prior to the Fed's decision-according to 5paisa. These sales indicate that investors had anticipated the rate hike.
• The Gulf: currencies pegged to the dollar, interest rates adjusted on the same day
The "Analysis of Economic Blocs" series previously highlighted-in the episode regarding the Gulf Cooperation Council-that Gulf states lack a single currency and a unified monetary policy, preferring instead to peg their currencies to the US dollar. The consequence became apparent on September 16. The UAE central bank stated that its benchmark rate is linked to the interest rate the Fed pays on bank reserves and serves as a floor for overnight rates in the Emirates, according to TradeArabia. The UAE rate reached 3.90%, exactly the level set by the Fed for September 17.
Unlike other Gulf states, Kuwait pegs its currency to a basket of currencies rather than directly to the dollar, and it was the only Gulf state that did not raise interest rates.
• BRICS+: Central banks don't all follow the Fed, but currencies react
The final installment of this series argued that interest rates in the BRICS+ and AfCFTA blocs are less sensitive to decisions made by the Fed or the ECB. The rate hike on September 16 tests this claim in two ways.
For BRICS+ nations with dollar-pegged currencies, the claim does not hold true: the United Arab Emirates, a BRICS+ member, followed the Fed's move on the same day. For nations with floating currencies, the claim holds true only regarding the central bank's interest rate. The Reserve Bank of India maintained its repo rate at 5.25% in August and does not mechanically mirror Fed decisions, according to INDmoney. However, the rupee depreciated, and foreign investors had already reduced their exposure to India prior to the decision. A BRICS+ central bank may be able to maintain its interest rate, but it cannot halt the impact of a stronger dollar on its currency and capital flows.
• China: where the Fed interest rate no longer dictates capital allocation
The People's Bank of China maintained its seven-day repo rate at 1.40% in early July-well below the Fed's rate-according to investingLive. China can afford such a spread because its central bank sets a daily reference rate for the yuan, allowing the currency to fluctuate by no more than 2% around that rate on the market, as reported by Reuters. The Chinese central bank set the reference rate weaker than market estimates to prevent excessive appreciation of the yuan.
Interest rate theory explains this dynamic. When credit-funded operations no longer determine capital flows, allocation shifts to other mechanisms: administrative decisions, capital controls, and state-directed lending. In China, investors cannot freely move their funds into higher-yielding US securities; consequently, Fed rate hikes do not attract Chinese capital the way they attract Indian capital.
However, China's autonomy is partial and comes at a cost. The yuan remains influenced by the dollar's exchange rate, requiring the central bank to intervene daily via the reference rate to keep the currency within desired limits. While Chinese interest rates are set in Beijing, the yuan's exchange rate cannot ignore developments in Washington.
• Sanctioned nations and oil
Countries largely shut out of dollar-based financing and payment systems due to sanctions are also relatively insensitive to Fed interest rates, albeit for a different reason. Interest rate theory describes a scenario where barriers cause the risk premium demanded by financiers to rise faster than potential returns.
Transactions become unfinanceable due to the legal and political environment, rather than the level of interest rates. Interest rate theory cites the sanctions imposed on Russia after 2014 and 2022 as examples: price differentials widened significantly, yet access to financing, payment channels, and eligible partners was restricted.
For such a state, a higher Fed interest rate makes little difference, as dollar-denominated credit was already inaccessible; the cost incurred stems from the barriers themselves. The conflict continues into 2026: the EFE agency, cited by BURSA, reports on China challenging US sanctions against buyers of Russian oil.
Payment infrastructures built to bypass the dollar do not yet form a unified system. At the New Delhi summit on September 12-13, BRICS nations adopted a declaration acknowledging the work of the BRICS Payments Task Force regarding the interoperability of payment channels and the use of national currencies in trade. The declaration notes that there is no "one-size-fits-all" solution and calls on the group to continue discussions on practical solutions, according to the text cited by Interfax. Interfax observes that BRICS nations have not made significant progress regarding cross-border settlements. India's Ministry of External Affairs stated that there is no proposal for a BRICS currency and that settlements in national currencies are encouraged as a complement to the global payment system, according to IANS, cited by Telangana Today.
The cause cited by the Fed and the ECB for current inflation-rising energy costs-lies beyond the Fed's control.
Warsh stated that while the Fed cannot stop the rise in oil prices on its own, it can prevent inflationary pressures from spreading to the rest of the economy, according to CNBC.
The price of Brent crude fell 0.7% on Thursday to $105.05 per barrel, following a 2.7% drop on Wednesday, amid reports that Saudi Arabia was offering crude oil cargoes via Oman, according to Reuters. Oil prices moved in response to supply news rather than the Fed's decision.
The final installment of the BURSA report attributed higher interest rates in the West to the increased cost of production resulting from its relocation within the respective blocs. In September, central banks cited a different primary cause: the European Central Bank (ECB) attributed the September 10th rate hike to inflationary pressures stemming from the conflict in the Middle East, according to a statement released by the ECB.
• Four degrees of autonomy regarding dollar interest rates
The rate hike on September 16th allows for a comparison that is not as clearly visible in Fed decisions made during calmer periods. The same decision produced different effects depending on the extent to which each state can determine its own interest rates, exchange rates, and capital flows. Four scenarios emerge from the facts presented above.
Gulf states with currencies pegged to the dollar cannot set their own interest rates: they adopted the Fed's hike on the same day, with the UAE matching the Fed's level exactly. India sets its own interest rates but cannot fully protect its exchange rate: the Reserve Bank of India did not follow the Fed, yet the rupee fell and foreign investors withdrew funds. China sets its interest rates and largely controls its exchange rate and capital outflows: Chinese interest rates remain well below Fed rates, and the yuan moves only within limits set daily by the central bank. However, this autonomy is partial, and the price paid is that described by interest rate theory: capital allocation is driven by administrative decisions rather than interest rates.
Sanctioned states are minimally affected by Fed interest rates because they have already lost access to dollar-denominated credit. Their autonomy regarding US interest rates stems not from monetary strength but from exclusion, and the cost paid is the burden of barriers. BURSA interprets this comparison as suggesting a measure of the Fed's interest rate influence outside the United States: specifically, the extent to which other economies are unable to escape its impact. The more a country relies on the dollar for exchange rates, financing, and trade, the more the Fed's interest rate dictates the cost of money within that country. A single Fed decision is insufficient to confirm this interpretation; subsequent decisions may validate it.
• Romania: Interest rates on loans in lei follow the National Bank of Romania (BNR), not the Fed
On August 10, the BNR Board maintained the monetary policy rate at 6.50%, with the deposit facility rate at 5.50% and the lending facility rate at 7.50%, according to the BNR statement published by BURSA. The BNR's next monetary policy meeting is scheduled for October 8, 2026, according to the same statement.
The interest rate on overnight interbank deposits remained at 5.64%, according to BURSA-falling within the range established by the BNR.
The National Institute of Statistics (INS) reported an annual inflation rate of 6.17% for August 2026, down from 8.16% in July, according to Agerpres. In August, the BNR raised its inflation forecast for the end of 2026 to 6.1% (up from 5.5%) and projects inflation of 3.4% by the end of 2027, according to the same Agerpres report.
The Fed's decision reaches Romania through two channels. 1.The first channel is the exchange rate: the NBR set a reference rate of 4.5844 lei per dollar for September 17, according to quotes published by BURSA, and imported oil and gas are paid for in dollars. A stronger dollar raises the cost in lei of imported fuels, even if the price of crude oil remains unchanged.
2.The second channel is state debt. The head of the State Treasury, Ştefan Nanu, in an interview with Reuters, estimated a gross financing requirement for 2026 of between 275 and 285 billion lei, with over 150 billion lei earmarked for debt refinancing. In the external issuance on February 25, Romania raised approximately 4.7 billion euros-including a 2-billion-dollar, 10-year tranche-according to a Ministry of Finance statement published by Agerpres. Romanian dollar-denominated bonds are priced relative to US Treasuries; the yield on the 10-year US Treasury note stood at 5.02% at the close of the US market on Wednesday, according to The Motley Fool. Consequently, a new dollar issuance by Romania would come at a higher cost.
In terms of the four scenarios, Romania's position vis-à-vis the dollar is similar to India's: the National Bank of Romania (BNR) sets its own interest rates, and the Federal Reserve's decisions impact the Romanian economy through the exchange rate and dollar-denominated debt, rather than through interest rates on leu-denominated loans. However, Romania's strongest link is with the euro, not the dollar: over 70% of Romania's exports go to the European Union, according to Eurostat data cited in the BURSA Globalization Index.
Therefore, the ECB's decision on September 10 and the BNR's upcoming decision on October 8 have a greater impact on borrowing costs in Romania than a Fed rate hike.

 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur



Reader's Opinion