 English


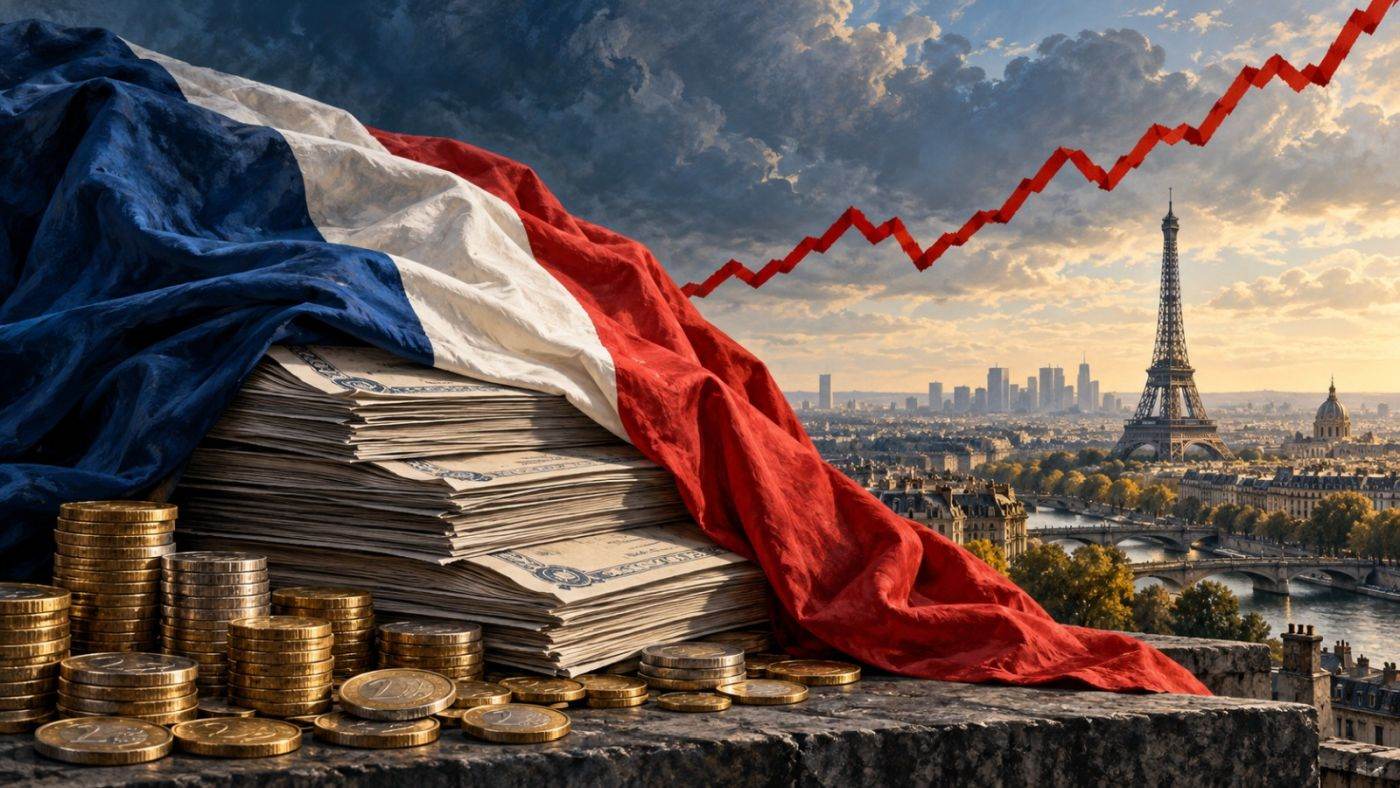
France is discovering just how costly a lack of confidence can be, as the yields on its ten-year bonds briefly surpassed the 5% threshold, for the first time since 2002, while the spread against German bonds climbed to approximately 1.6 percentage points, the highest level in 15 years, according to an analysis by the German news outlet Tagesschau (part of the ARD 1 television network).
Behind these figures lies a question that extends well beyond France's borders: how much can the finances of a major European economy deteriorate before the resulting tensions become a problem for the entire monetary union? The data presented by Tagesschau point to mounting pressure on Paris, at a time when implementing budgetary decisions is becoming increasingly difficult from a political standpoint.
To the general public, the bond market may seem like a distant realm, filled with abstract percentages and transactions. For a government, however, it is the place where political promises collide with the cost of money. A state that spends more than it collects must borrow to cover the difference, while simultaneously repaying or refinancing maturing debt. If investors demand a higher return to purchase its bonds, future financing becomes more expensive, and the government's budgetary room for maneuver gradually shrinks. According to International Monetary Fund estimates, cited by the source, France's public debt is projected to reach 118.5% of its gross domestic product (GDP) by the end of 2026, up from approximately 86% at the onset of the sovereign debt crisis in 2010, while the budget deficit is estimated at around 5.4% of GDP. Under these circumstances, France is now offering higher yields than Italy, a shift in standing that highlights the extent to which investor perception has changed.
A debt-to-GDP ratio exceeding 100% does not imply that the entire amount must be repaid in a single year, nor does it mean that bankruptcy is inevitable. What matters are maturity profiles, the average cost of financing, state revenues, and the economy's growth potential. However, a persistent deficit means that the need for borrowing continues. When this requirement coincides with higher interest rates, fiscal adjustment becomes more challenging: the state must secure funds both for its ongoing policies and to cover the cost of financing them.
This effect does not manifest entirely overnight. Bonds already issued with fixed interest rates retain their original terms until maturity. The pressure builds gradually as the state takes on new debt and refinances maturing obligations. It is precisely this time lag that can create a dangerous illusion of comfort; markets may show signs of strain today, while a portion of the budgetary consequences accumulates in the years to come. A hypothetical calculation illustrates the scale: for euro100 billion in new financing, a one-percentage-point increase in interest rates translates to an additional annual cost of euro1 billion, assuming all other conditions remain constant. While this example is not an estimate of France's specific financial burden, it explains why seemingly minor fluctuations in yields can radically alter the debate surrounding the budget.
The central authorities in Paris are following a fiscal correction path established at the European level. In a recommendation adopted in January 2025, the Council of the European Union called on France to eliminate its excessive deficit by 2029. The document set limits on the nominal growth of net expenditure: 0.8% for 2025, 1.2% annually from 2026 to 2028, and 1.1% for 2029. The established European benchmarks remain a deficit of 3% of GDP and a debt-to-GDP ratio of 60%.
In practice, such commitments necessitate choices that have tangible impacts on the economy and daily life. Cutting certain expenditures may trigger opposition from beneficiaries; raising taxes could dampen consumption, investment, or the willingness of taxpayers to accept further sacrifices; and deferring measures, while temporarily preserving political calm, may only prolong reliance on borrowing. The challenge lies in finding a pace of adjustment that is both credible enough for investors and manageable enough for the economy.
This is where the risk of a vicious cycle emerges. If financing becomes more expensive, interest expenses may absorb a larger share of revenue; conversely, if fiscal adjustment slows economic activity too sharply, tax receipts may fall short of expectations. On the other hand, if the government abandons fiscal consolidation to avoid political costs, investors may demand an additional risk premium. None of these outcomes is inevitable, yet they all illustrate why the credibility of a fiscal program is just as important as its announcement.
In this context, attention inevitably turns to the European Central Bank, the authors of the Tagesschau analysis argue. Can the ECB intervene and if so, through what mechanism and under what conditions?
In July 2022, the ECB approved the Transmission Protection Instrument, known by the acronym TPI. Its purpose is to counter disorderly and unjustified market movements that threaten the transmission of monetary policy within the euro area. Purchases have no pre-set limit; their scale depends on the severity of the risks.
To activate the TPI, the ECB assesses factors such as compliance with the European fiscal framework, debt sustainability, and macroeconomic policies. The existence of an excessive deficit procedure does not automatically preclude access; what also matters is whether the state in question is deemed to have taken effective action in response to the Council's recommendations. Consequently, intervention requires an assessment it does not follow automatically simply because interest rates exceed a certain level.
For Paris, the implications are significant. A mechanism designed to safeguard the functioning of the monetary union cannot be treated as a guaranteed source of cheap financing. For the ECB, the challenge lies in distinguishing between instances where investor pressure reflects budgetary risks and instances where market dysfunction threatens the common monetary policy. Intervening too early or too late carries different types of risk.
Europe also has the OMT framework, announced in September 2012. This allows for operations in the secondary sovereign bond market, but it entails strict conditionality linked to an appropriate program under European financial assistance mechanisms. The existence of this instrument demonstrates an institutional capacity to respond, while also highlighting that such support may come with significant economic and political obligations.
European risk must be viewed through the lens of these concrete mechanisms. In a contagion scenario, the cited analysis suggests that investors might re-evaluate the bonds of other nations as well; banks could become more cautious, and companies might face higher financing costs. This is a risk scenario, not a description of an outcome that has already unfolded.
A rise in French yields does not, in itself, prove that the Eurozone has entered a new systemic crisis. After all, investors may accept a multi-year correction, provided they have reason to believe in it. What becomes increasingly difficult to finance is a recurring sequence of promises, deferrals, and compromises that perpetually push the bill into the future. Higher interest rates make the cost of this bill increasingly apparent, and the French government must demonstrate that it can regain its room for policy maneuver before debt-servicing costs restrict it even further.








 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur
































Opinia Cititorului