 English
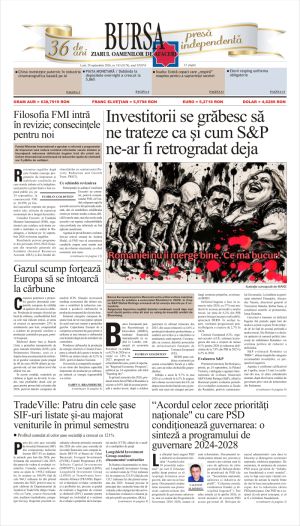
The revision of the rules governing how the Fund designs lending programs and sets the conditions states must meet to receive funds was publicly announced on Thursday, September 24, in IMF Press Release No. 26/299. This move comes against the backdrop of repeated program failures-issues criticized by numerous economists over the decades.
The Executive Board of the International Monetary Fund (IMF)-the body managing the day-to-day operations of the Washington-based institution-concluded the review of these rules on September 14, 2026.
The findings concern programs from the 2018-2024 period financed through the Fund's general resources (General Resources Account, GRA) and the fund dedicated to low-income countries (Poverty Reduction and Growth Trust, PRGT).
• What the review changes
According to the IMF statement, participants in the Executive Board meeting noted that while the Fund responded rapidly to successive shocks during the period under review, restoring medium-term external balance remained difficult for some states-particularly where shocks were recurrent, vulnerabilities were deep-seated, or reforms were insufficiently implemented. The Reuters news agency reported, in an article by Andrea Shalal, that the IMF aims to focus conditions on a smaller number of structural reforms that yield a greater economic impact. The Executive Board endorsed recommendations calling for fiscal adjustments based on both revenue increases and spending cuts, improved risk assessment, and more realistic estimates of available financing. According to Reuters, the Fund stated that it seeks better program implementation rather than a lowering of standards.
• The dispute over early adjustment
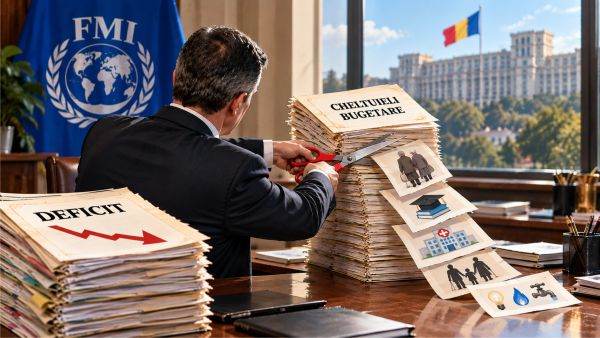
The most contentious aspect of the reform concerns the timing of when a borrowing state must reduce its deficit. The IMF advocates for fiscal adjustment that is implemented early and sustained over time-associating this with a higher likelihood of program success-provided it is feasible and accompanied by measures to support economic growth and adequate social spending for vulnerable populations, Reuters reported.
Oxfam International, a global organization dedicated to fighting poverty, issued a response on September 24. Nabil Abdo, a senior policy advisor at Oxfam International, stated that civil society organizations had warned the IMF that front-loaded adjustment-adjustment concentrated at the start of a program-effectively translates into drastic, abrupt spending cuts borne by ordinary citizens; he noted that these warnings were ignored, even though numerous Executive Board members had voiced similar concerns. However, Nabil Abdo welcomed the Executive Board's recognition of the need to assess the impact of programs on income distribution and called for this requirement to be effectively implemented within the programs.
In an analysis released prior to the September 14 meeting, Oxfam International calculated that the median annual budget deficit reduction target required by the IMF rose from 0.21% of Gross Domestic Product (GDP) during the 2012-2017 period to 0.85% of GDP for 2018-2025.
Also ahead of the meeting, on September 11, the European Network on Debt and Development (Eurodad)-a coalition of non-governmental organizations-published an open letter signed by over 130 organizations, calling on the IMF Executive Board to reject a return to front-loaded fiscal adjustment.
• Why states turn to the IMF
In the BURSA analysis, the dispute between the IMF and Oxfam International centers on who bears the cost of adjustment and at what pace, rather than whether adjustment can be avoided.
A state seeks IMF funding when it can no longer meet its external financing needs on manageable terms. The cause may be the debt burden, but also a loss of access to financial markets, capital flight, or an external shock, such as the pandemic. When interest and installment payments consume an excessive share of state revenue, new loans go toward servicing old debt rather than funding investments, while private creditors demand increasingly higher interest rates or refuse to lend to the state in question.
An IMF program can lower borrowing costs through the funds provided by the Fund and by instilling creditor confidence that the state will meet its obligations; the outcome depends on the program's credibility and the debt outlook. In the main review document, the IMF aims for its financing to attract other creditors as well.
An IMF program can solve three different problems. The first is the short-term lack of money: the state receives the necessary funds to pay its immediate obligations. The second is the ability of the state to bear its debt in the long term without its payment taking an increasing part of the revenues. The third is the ability of the economy to produce the revenues from which the state pays its debt. A program that solves only the first problem leaves the state, at the end, in the situation from the beginning: creditors demand high interest rates again, and the state needs a new program.
The IMF acknowledged through the review that rebalancing over the medium term remained difficult where shocks have recurred, and the review documents state that it should not be automatically assumed that a country will need a new program after the end of the previous one. The question remains open as to whether an IMF program can stabilize a state's finances without restoring the economy's ability to produce the income needed to pay the debt.
The IMF associates early adjustment with higher chances of program success; in the BURSA analysis, it also shortens the period in which the state pays high interest, before the debt increases even more. The government can decide, through the budget, who bears the reductions: pensioners, public sector employees, social aid beneficiaries or taxpayers, through higher taxes. However, the government cannot eliminate the obligation to pay the debt. Postponing the adjustment may reduce the immediate social cost, but risks increasing the debt and the cost of financing. The acceleration of the adjustment can limit the growth of the debt, but it can reduce the economic activity and, with it, the budget revenues; the result depends on the structure of the measures, the financing conditions and the capacity of the economy to bear the adjustment. Oxfam International is not asking for the adjustment to be abandoned, but for the staggered spending cuts over several years. The rapid adjustment, preferred by the IMF, increases the cost in the first years, and when it is done by reducing spending, it is borne by those who depend on public spending, in the current system.
• The new framework for the debt of poor countries
The IMF and the World Bank, the development financing institution also based in Washington, approved in September changes to the joint framework for analyzing the sustainability of the debt of low-income countries (Low-Income Country Debt Sustainability Framework, LIC-DSF), Reuters reported on September 21. According to the agency, the revised framework takes a closer look at domestic debt and long-term risks, including those related to climate change, and is due to apply from the second half of 2027.
Allison Holland, deputy director of the IMF's Africa Department, who worked on the new framework, told Reuters that about 14 percent of low-income countries are already in debt distress, and another 33 percent are at high risk of becoming so; among states with emerging markets, 23% present a high risk of public debt difficulties. According to Allison Holland, recent shocks have brought the number of these countries back to pre-pandemic levels, and the goal of the new framework is for vulnerabilities to be identified earlier and more precisely.
According to figures presented by Allison Holland, 47% of low-income countries are already in debt distress or at high risk of becoming so.
• Application of the reform
The IMF specified, in the question and answer document published with the revision, that the new rules are applied in stages.
First, the operational guide is updated and analysis tools are prepared for the teams that negotiate the programs with the states; then the new tools are applied to the requested programs and, where appropriate, to ongoing programs.
The Fund intends to evaluate the programs more systematically at their end.
• What this means for Romania
Romania does not currently have a loan program with the IMF; the Fund assesses the country's economy through the annual consultations mandated by Article IV of its Articles of Agreement.
In the conclusions of the 2025 consultation, approved by the Executive Board on November 7, 2025, the IMF assessed that the fiscal reform package for 2025-2026 represents an important step. It further noted that full implementation of this package-combined with additional adjustment measures starting in 2027 to reduce the deficit below 3% of GDP-is essential for restoring fiscal and macroeconomic sustainability.
In the report on the same consultation, published in November 2025, IMF experts noted that the fiscal package-which aimed to reduce the deficit below 6% of GDP by 2026 and included a VAT hike-had helped avoid a suspension of European structural funds and a downgrade of the sovereign credit rating below investment grade.
Recommendations arising from Article IV consultations constitute assessments and advice, not binding conditions. In the absence of an IMF program, the cost of Romanian state debt depends on financial market conditions and how investors perceive the risks associated with the Romanian economy, including budget execution.
Should Romania request a loan program in the future, the IMF rules in effect at that time would apply; for the coming years, these are the rules approved in September 2026 and implemented gradually, featuring fewer conditions and a focus on encouraging budget adjustment from the start of the program.
• What this means for investors
The World Bank uses debt sustainability analyses to determine the mix of loans and grants that low-income countries receive from the International Development Association (IDA), the World Bank institution that finances the poorest nations.
Reclassifying a country under the new framework can alter the terms of official financing and, consequently, the risk premium private creditors demand for that country's debt.
Investors with exposure to the sovereign debt of low-income countries have an interest in monitoring the implementation of the revised framework, scheduled for the second half of 2027.
The current revision changes how the IMF requires states to reduce their deficits, not the underlying reasons why states end up seeking funds from the Fund.
States return to the IMF when a program has provided necessary short-term funding but failed to restore the economy's capacity to generate the revenue needed to service the debt.
Romania, which does not currently have an IMF program, faces the same challenge: the deficit must be reduced without diminishing the economy's revenue-generating capacity-a factor that also determines the cost at which the state will borrow in the coming years.
 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur

Reader's Opinion