 English
The European Bank for Reconstruction and Development (EBRD), a London-based international financial institution, projects that Romania's economy will contract by 0.2% in 2026 and grow by 1.8% in 2027-forecasts unchanged since June-according to the "Regional Economic Prospects" report published on September 24 under the title "Running dry."
In the first half of 2026, Romania's gross domestic product (GDP) fell by 0.8% compared to the same period the previous year, following a sharp decline in the final quarter of 2025 driven by a 4.6% drop in manufacturing output and a decline in services and retail sales, the report indicates. Construction activity increased, however, thanks to European Union (EU)-funded infrastructure projects.
The EBRD attributes the economic contraction to fiscal consolidation and inflation, both of which have dampened household spending. Inflation rose to 9.7% in May 2026 and fell to 6.3% in August but remained the highest in the EU; the EBRD warns that the depreciation of the leu against the euro and higher energy prices could prolong the rise in prices.
The budget deficit for January-July 2026 was 37% lower than in the same period last year, and the EBRD considers the full-year target of 6.2% of GDP to be achievable. In the same report, the institution forecasts 2.7% growth for Bulgaria in 2026.
The European Commission (EC), the EU's executive body, had projected-in its May forecast-growth of only 0.1% for 2026 and a reduction in the deficit from 7.9% of GDP in 2025 to 6.2% in 2026.
• S&P Assessment
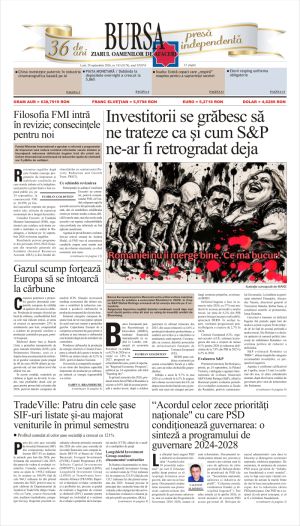
On September 24, Interim Prime Minister Ilie Bolojan received a delegation from the international financial rating agency S&P Global Ratings (S&P) at Victoria Palace; the delegation was in Bucharest for a periodic assessment of Romania's economic and fiscal developments, according to a government statement. The meeting was attended by Finance Minister Alexandru Nazare, State Treasury Director General Ştefan Nanu, and the Prime Minister's honorary advisor, Ionuţ Dumitru.
The government reported that the budget deficit for the first seven months of the year had decreased by over 28 billion lei compared to the same period last year. Ilie Bolojan expressed optimism that politicians concerned with Romania's stability would continue the policy of deficit reduction.
S&P rates Romania at "BBB-"-the lowest rung of the investment-grade category-with a negative outlook.
The agency affirmed the rating on April 3 and again on May 15-outside the announced schedule-following the collapse of the governing coalition due to a no-confidence vote in Parliament.
The Ministry of Finance stated at the time that the next scheduled rating publication was set for October 2, 2026.
In April, S&P had warned that it might downgrade Romania if deficit reduction deviated significantly from expectations, including instances where weak economic growth diminished the impact of fiscal measures. On July 31, Fitch Ratings (Fitch) announced that it was maintaining Romania's rating at "BBB-" with a negative outlook, after the Government challenged the rating committee's initial decision and presented additional information.
On September 18, a Fitch analyst told Bloomberg that Romania has increasingly little time to avoid a downgrade to speculative grade, as the prolonged political crisis jeopardizes its fiscal credibility.
Fitch will re-evaluate Romania in January 2027.
In August, Moody's Ratings (Moody's) confirmed Romania's rating at "Baa3"-the agency's lowest investment-grade tier-also with a negative outlook, according to the agency's statement.
Thus, all three major credit rating agencies keep Romania at the lowest investment-grade level, with a negative outlook.
• S&P Assessment
On September 24, Interim Prime Minister Ilie Bolojan received a delegation from the international financial rating agency S&P Global Ratings (S&P) at Victoria Palace; the delegation was in Bucharest for a periodic assessment of Romania's economic and fiscal developments, according to a government statement. The meeting was attended by Finance Minister Alexandru Nazare, State Treasury Director General Ştefan Nanu, and the Prime Minister's honorary advisor, Ionuţ Dumitru.
The government reported that the budget deficit for the first seven months of the year had decreased by over 28 billion lei compared to the same period last year. Ilie Bolojan expressed optimism that politicians concerned with Romania's stability would continue the policy of deficit reduction.
S&P rates Romania at "BBB-"-the lowest rung of the investment-grade category-with a negative outlook.
The agency affirmed the rating on April 3 and again on May 15-outside the announced schedule-following the collapse of the governing coalition due to a no-confidence vote in Parliament.
The Ministry of Finance stated at the time that the next scheduled rating publication was set for October 2, 2026.
In April, S&P had warned that it might downgrade Romania if deficit reduction deviated significantly from expectations, including instances where weak economic growth diminished the impact of fiscal measures. On July 31, Fitch Ratings (Fitch) announced that it was maintaining Romania's rating at "BBB-" with a negative outlook, after the Government challenged the rating committee's initial decision and presented additional information.
On September 18, a Fitch analyst told Bloomberg that Romania has increasingly little time to avoid a downgrade to speculative grade, as the prolonged political crisis jeopardizes its fiscal credibility.
Fitch will re-evaluate Romania in January 2027.
In August, Moody's Ratings (Moody's) confirmed Romania's rating at "Baa3"-the agency's lowest investment-grade tier-also with a negative outlook, according to the agency's statement.
Thus, all three major credit rating agencies keep Romania at the lowest investment-grade level, with a negative outlook.
• Why economic decline matters for debt
Economic decline and high interest rates reinforce each other.
When the economy contracts, the state collects less tax revenue than projected, making the deficit target harder to achieve.
Higher market yields do not alter the interest rate on existing debt, but they gradually increase the state's interest expenses as maturing debt is refinanced and new loans are taken out; consequently, less money remains for investment.
However, the EBRD ties economic recovery precisely to investment-specifically investment funded by European funds. The link between economic decline and the deficit is not inevitable; investment from European funds and export growth can break this cycle.
Reducing the deficit requires economic growth to be sustainable, yet the higher taxes and lower spending used to achieve this reduction can actually delay that very growth.
In its 2026 Convergence Report, the European Commission indicated that Romania's public debt rose from 54.8% of GDP in 2024 to 59.3% in 2025, and is projected to reach 61.6% in 2026 and 63.4% in 2027, driven by a large primary deficit and rising interest payments.
Debt sustainability risks are high in the medium term, with debt projected to reach approximately 90% of GDP by 2036, according to the European Commission. The budget deficit is shrinking, yet public debt continues to rise: as long as the state runs a large annual deficit covered by new borrowing, the debt grows, even if the deficit itself is narrowing.
For this reason, rating agencies and investors evaluate not only the reduction in the annual deficit but also the level at which debt growth will eventually plateau.
Data from the Ministry of Finance indicate that the deficit reduction achieved in the first seven months was driven primarily by revenue: budget revenues rose by 11.2%, while expenditures increased by 2.9%.
A significant portion of this revenue growth stems from tax hikes rather than economic expansion. Without a resumption of economic growth, achieving sustainable increases in budget revenue will be difficult, and further deficit reduction may necessitate additional tax hikes or spending cuts.
• What a downgrade would mean
A downgrade by S&P would place Romania in the speculative-grade category according to that agency, though the country would retain investment-grade ratings from Fitch and Moody's.
Some investment funds rely on the lowest of the available ratings, while others use the median rating or follow the rules of the specific bond indices they track.
Consequently, a downgrade by S&P alone does not automatically compel all institutional investors to sell Romanian securities.
A second downgrade would push Romania's median rating into the speculative-grade category as well, potentially affecting the inclusion of Romanian bonds in indices that utilize this classification method and impacting the funds that track them. Romania approaches the S&P decision with a shrinking budget deficit, but also with a contracting economy and rising public debt.
Deficit reduction is proceeding according to target; economic growth is not.
So far, the reduction in the deficit has not lowered the interest rates at which the state borrows.
To lower them, the state must demonstrate that it can continue to reduce the deficit without prolonging the economic downturn.
Even before the S&P decision, investors are already demanding interest rates from the Romanian state that reflect the risk of a credit rating downgrade-one that has not yet occurred.
 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur

Reader's Opinion