 English
Investors had rushed to judgment ahead of the agency: five-year insurance against default on Romanian debt, known as a credit default swap (CDS), was already the most expensive among more than 60 investment-grade countries tracked by Bloomberg, while the yield on two-year leu-denominated bonds, at 6.52%, was the highest in the European Union (EU), as BURSA reported on September 28.
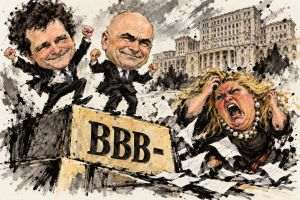
S&P Global Ratings (S&P) confirmed Romania's long- and short-term sovereign credit ratings at "BBB-/A-3” on October 2, 2026, with the decision coming at an extremely sensitive time for the Romanian economy, after five months of political crisis and as markets closely monitored the authorities' ability to continue fiscal consolidation.
The outlook remains negative, amid risks related to fiscal consolidation, the reduction of external imbalances and prolonged political uncertainty, according to S&P Global Ratings. Romania's Ministry of Finance (MF) communicated the decision immediately after the publication of S&P's report.
What investors betting on a downgrade lost
According to Reuters, five-year credit default swaps traded at levels that had anticipated a two-notch downgrade to "BB” from the beginning of 2025, reflecting concerns over the pace of debt accumulation and political tensions that weakened the pro-EU coalition.
Investors who bought CDS protection at high levels or shorted Romanian bonds built positions around a scenario that did not materialize. The mechanics of the loss are straightforward: a CDS purchased at a high premium becomes cheaper as soon as downgrade risk falls, reducing the market value of the position accordingly. At the same time, Romanian bonds that these investors sold short rise in price when credit risk declines, generating losses when the short positions are covered.
Currency and yield volatility over the past two weeks was driven by political uncertainty, while Romanian 10-year bond yields had risen by 60 to 80 basis points during that period, reaching one-year highs.
The partial reversal of these moves following S&P's decision represents the concrete loss for those who had bet on a downgrade.
Guillaume Tresca, senior emerging markets strategist at Generali Asset Management, had estimated the probability of an S&P downgrade for Romania at around 25%, indicating that maintaining the rating was the base-case scenario for most analysts. Therefore, the market had priced in a downgrade at a significantly higher level than reflected in analysts' estimates, with the difference representing the risk premium accumulated in instruments that are now losing value.
Consequences for Romania
S&P explained the decision to maintain the rating by its short-term expectation that Romania will manage to form a government that will adopt a credible fiscal framework for 2027-2028, noting that, despite the political deadlock in May, fiscal consolidation and the absorption of EU funds remained on the expected trajectory for 2026.
Interim Finance Minister Alexandru Nazare said that "compliance with fiscal commitments and sustained absorption of European funds weighed decisively” in S&P's decision. Nazare added, according to a statement from the Ministry of Finance, that the result is important but insufficient.
The negative outlook signals that the risk of a downgrade persists in the absence of credible progress in correcting deficits, while S&P warns that Romania's high external financing needs and the significant holdings of public debt by non-resident investors make the country vulnerable to changes in market confidence.
Maintaining the rating does not reduce the interest rates the state pays on debt that has already been refinanced at high costs. Interest expenses increased by 26.7% compared with the same period last year, according to Ministry of Finance data cited by the Romanian press. In the first seven months of 2026, the state paid more than 40 billion lei in interest, 26.5% more than during the same period a year earlier.
The Ministry of Finance announced higher interest rates for new Tezaur and Fidelis government bond issues in October 2026, as the yield on 10-year government bonds had reached approximately 7.6% at the end of September. For the Tezaur programme, available from October 5 to November 6, 2026, the new annual interest rates are 6.50% for the one-year maturity, 7% for three years and 7.50% for five-year securities, up from previous yields of 6.20%, 6.75% and 7.15%.
Political deadlock remains the key risk
S&P's decision gives Romania some breathing room, but does not eliminate the risks. S&P says it could lower Romania's ratings if the prolonged government-formation process, which followed the coalition's breakup in May 2026, prevented the reduction of the budget deficit in 2027 and 2028.
President Nicuşor Dan announced on September 30, 2026, that he would summon parliamentary parties to the Cotroceni Palace on Monday for new consultations and that he would nominate a new candidate for prime minister on the same day. The cabinet proposed by Siegfried Mureşan received 182 votes in favor, below the 233 votes required for investiture.
This would be the fourth prime ministerial nomination made by Nicuşor Dan since the political crisis began in May.
Kathryn Exum, co-head of sovereign research and strategy at Gramercy, said that a downgrade would likely trigger forced selling that would widen bond spreads. The risk of this scenario has not disappeared: S&P's negative outlook means that another unfavorable assessment remains possible if the formation of a government capable of adopting the 2027 budget is delayed.
A Fitch Ratings (Fitch) analyst, in comments to Bloomberg in September 2026 and reported by the economic press, linked the maintenance of investment-grade status to the continued reduction of the deficit, the presentation of a credible 2027 budget and the establishment of a path toward a deficit of 3% of Gross Domestic Product (GDP). Fitch will reassess Romania in January 2027.
The National Bank of Romania (NBR) set the reference exchange rate at 5.3447 lei per euro on October 3, 2026, up 1.27% from the previous day, according to data published by the NBR.
The depreciation occurred before the publication of the S&P report and reflects the tensions accumulated during the week preceding the decision, rather than a reaction to it.
BURSA concluded on September 28 that investors were demanding interest rates from the state that reflected, among other things, the risk of a downgrade that had not occurred. S&P's October 2 decision partially validates that assessment: the rating remained unchanged, but high financing costs, elevated CDS levels and the negative outlook show that the structural imbalances that generated that risk premium have not disappeared.
The thesis is supported. Romania is facing three forces, and each is being challenged or defended on a different front. The first is the pro-European camp: the president, PNL, USR, UDMR and the interim Bolojan government. The second is PSD, which wants to govern and rejects Bolojan's economic model. The third is the sovereigntist camp, namely AUR and Georgescu.
On the legal front, the state is acting against the third force. The decision was not straightforward, however. The court left Georgescu under judicial supervision, while the two judges of the Court of Appeal had divergent opinions, so the decision on detention was taken only by a panel convened to resolve the disagreement. This shows that the courts are not united in their assessment of the case.
On the parliamentary front, the first force is confronting the second. The third stayed on the sidelines: AUR did not participate in the vote.
On the financial front, the rating has become a political argument, and your observation has a basis. S&P writes that, amid the deadlock, a government with limited powers maintained the fiscal trajectory and a public investment budget equivalent to 8.5% of GDP. Bolojan immediately used the wording to attribute the rating's maintenance to his measures and accused PSD of causing the crisis. Daniel Dăianu went even further, describing the Bolojan government's performance in correcting the deficit as exceptional.
The S&P text nevertheless contains arguments for both camps, and the halo you refer to comes from what each side chose to quote. The same report forecasts a 0.5% contraction of the economy in 2026, due to fiscal consolidation, inflation and declining real wages. These are precisely Grindeanu's arguments. Moreover, S&P calls for a government supported by a majority and a credible budget for 2027-2028. With 170 votes, such a majority does not exist without PSD. Thus, the agency endorses Bolojan's direction but sets a condition that only his political opponent can fulfill.
The result is that the rating gave Bolojan an image gain and left PSD with the power to decide.


 Euro
 Dolar SUA
 Franc elveţian
 Liră sterlină
 Gram de aur

Reader's Opinion